Quick answer
When a key supplier collapses or stops delivering, confirm whether an administrator or liquidator has been appointed, find out what happens to any deposits or goods you've paid for, and line up alternative suppliers straight away. New suppliers often want cash up front, so cash flow tightens. Forecast the next 13 weeks, then fund the stock and deposits you need with working capital sized to your trade.
Key points
- Deposits and prepayments to a failed supplier usually rank as unsecured debts.
- Replacement suppliers often ask for cash on order until they know you.
- Buying more stock in one hit can cost less than running out.
- Working capital funding can cover deposits and the temporary loss of trade credit.
- Creditor guides
- ASIC INFO 45 and INFO 74
- Security search
- ppsr.gov.au
- Unsecured options
- Typically $5,000 to $500,000
- Possible timing
- Same-day funding possible for smaller unsecured amounts
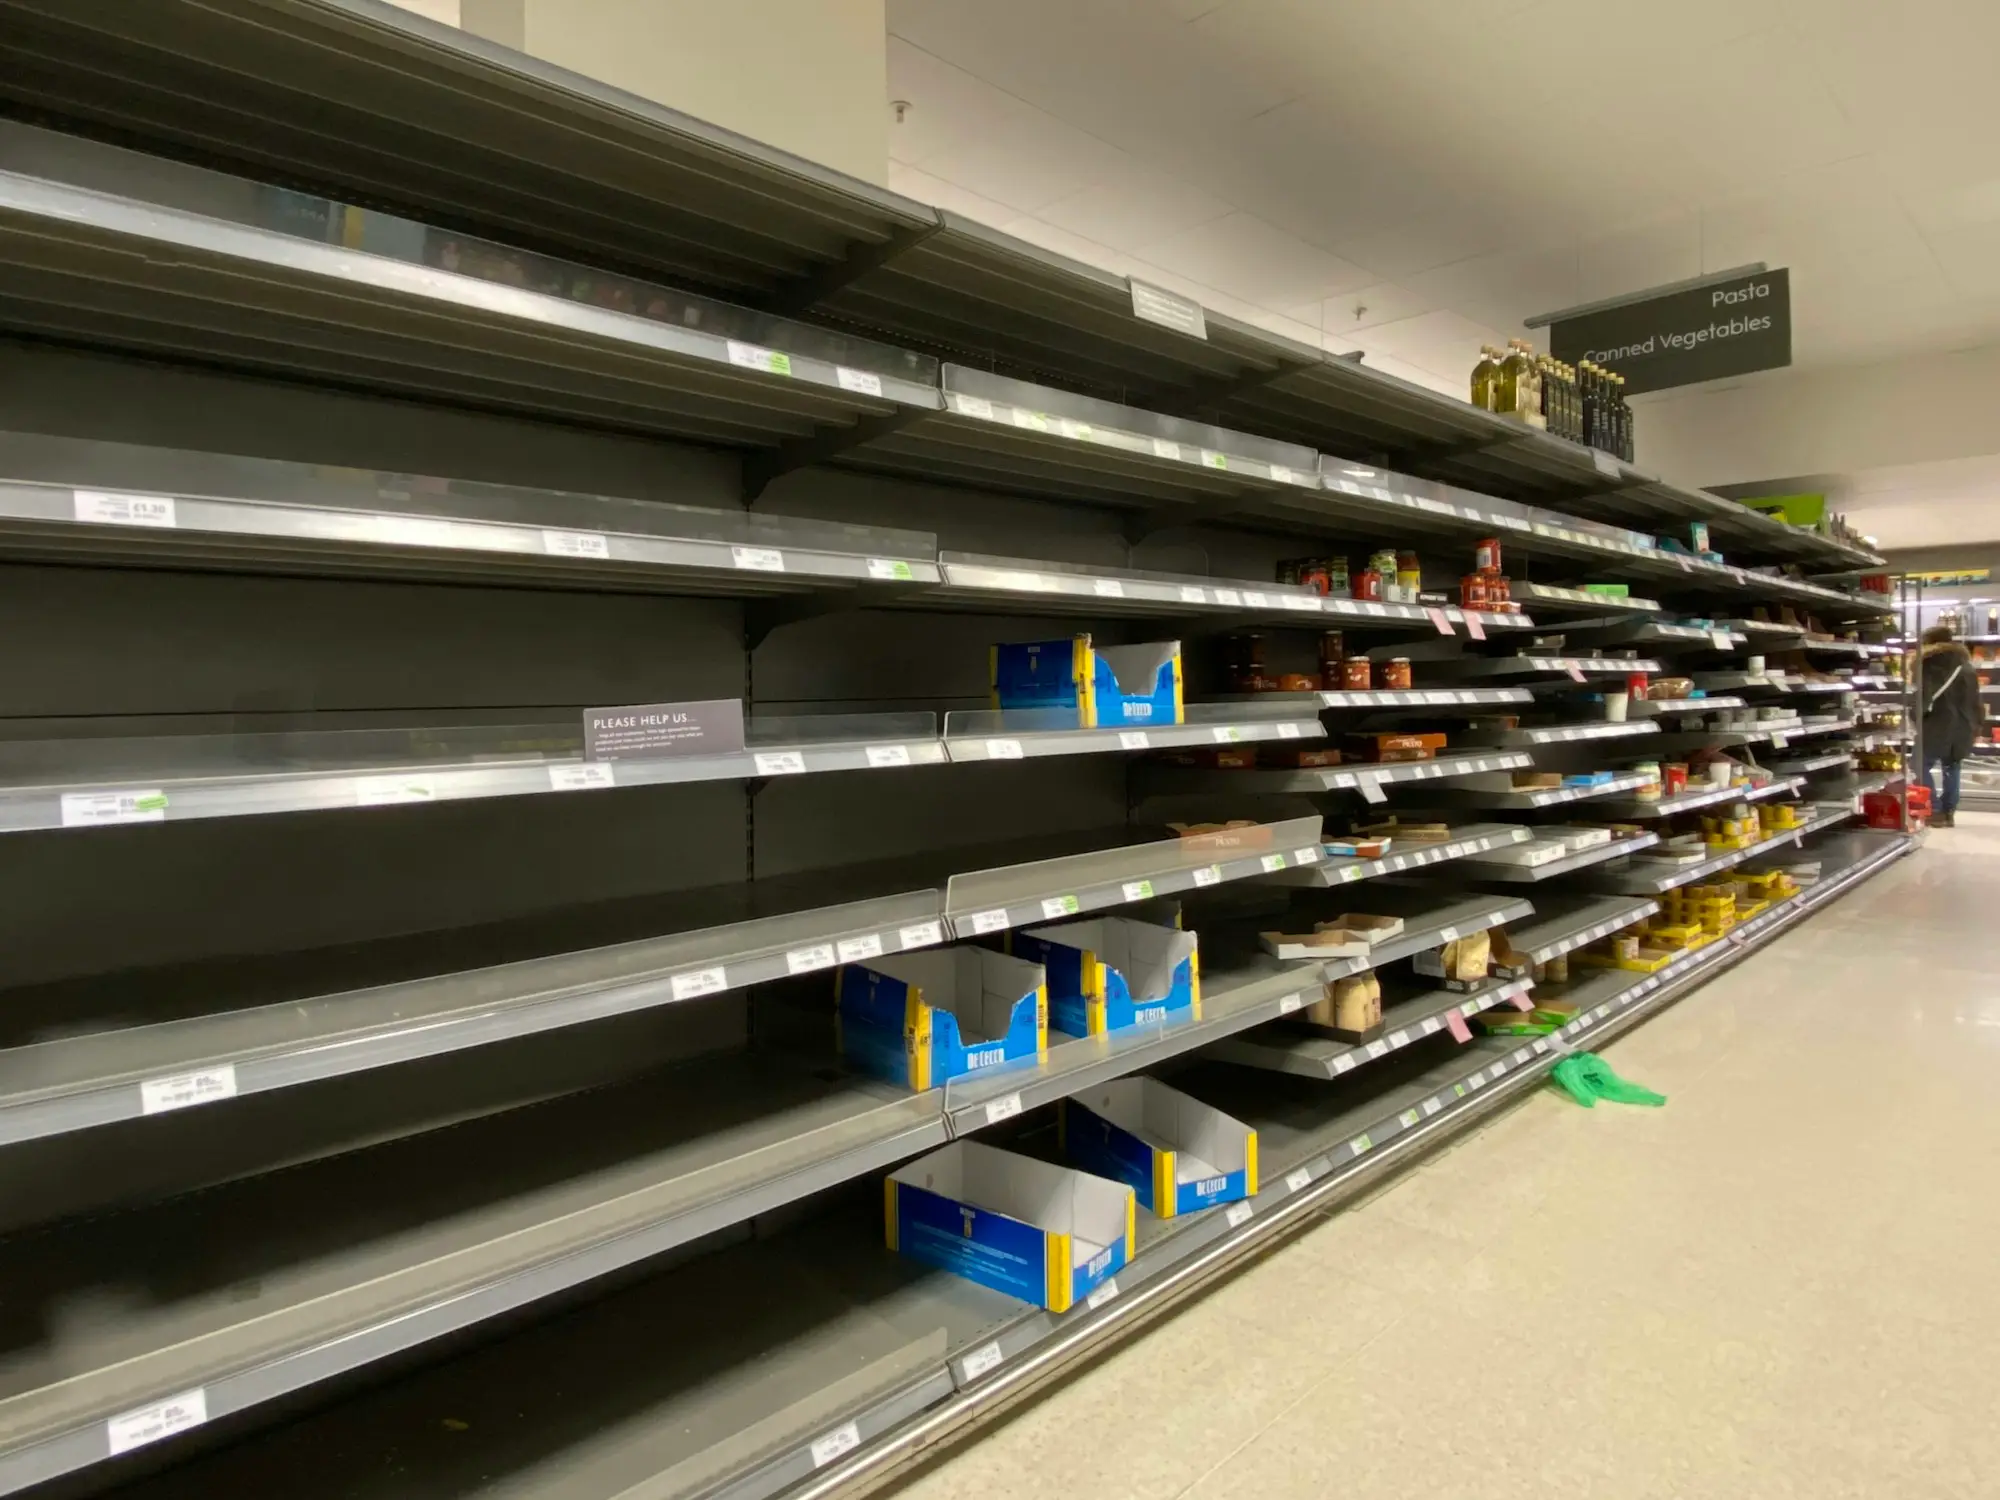
For many businesses one supplier is quietly essential — the only importer of a product line, the wholesaler who gives 60-day terms, the manufacturer who makes the part nobody else stocks. When that supplier goes into administration, closes a warehouse or just stops answering, the crisis is immediate: empty shelves, missed orders and customers asking questions.
This page covers how to steady the ship. The same steps sit under “Supplier failure” in our emergency action checklist.
What should you do in the first 24 hours?
- Find out what’s actually happened. Check ASIC’s published notices for an administrator or liquidator appointment, and get the appointee’s contact details.
- List what’s at stake: open orders, deposits paid, goods in transit, stock on consignment, and any money you owe them.
- Check your stock position — how many days or weeks of each affected item you have left.
- Call two or three alternative suppliers for availability, pricing, lead times and payment terms.
- Tell your key customers calmly if orders will be affected, with a realistic plan.
What should you do in the first week?
- Contact the administrator about undelivered orders and deposits. In a voluntary administration the business may keep trading, and the administrator may honour orders. ASIC’s guide to voluntary administration explains how creditors are kept informed and can vote on the company’s future.
- Lodge a proof of debt if you’re owed money and it’s a liquidation. ASIC’s liquidation guide says to attach invoices and supporting documents.
- Lock in replacement supply, even at a higher price at first. Running out usually costs more.
- Rework your cash forecast for cash-on-order terms. Our recovery cash-flow forecast guide shows how.
- Talk to your own lenders or landlord early if the change will squeeze your cash for a few months.
Who should you call?
| Contact | Why |
|---|---|
| Administrator or liquidator | Orders, deposits, goods in transit, ongoing supply |
| Alternative suppliers | Availability, price, lead times, terms |
| Freight forwarder or customs broker | Goods in transit or held at port |
| Key customers | Revised dates, substitutes |
| Your accountant | Set-off, GST, forecasting |
| Your bank | Overdraft limits, short-term options |
Why does a supplier failure squeeze cash so hard?
Losing a good supplier often means losing trade credit, not just product. The maths is simple and brutal:
| Before | After |
|---|---|
| 30- or 60-day terms | Cash on order or deposit up front |
| Small, frequent orders | Larger minimum orders |
| Local stock | Longer lead times, more stock on hand |
| Deposit in the old supplier’s hands | Probably lost or delayed |
So even a profitable business can suddenly need several weeks of extra working capital. If that’s where you are, see what’s possible with a quick enquiry — a real person will talk it through, with no credit check at enquiry stage.
How do businesses fund the switch to a new supplier?
- Unsecured cash-flow funding — typically $5,000 to $500,000, sized on turnover and bank statements, to pay deposits and larger stock orders. Same-day funding is possible for smaller amounts. See unsecured emergency cash.
- A line of credit — draw as orders are placed, repay as stock sells.
- Property-secured loan — for larger or longer needs, from $20,000 to $5,000,000.
- Restocking funding — see restocking after a loss.
Illustrative example only: a hardware store’s main importer of garden products enters administration two weeks before spring. The new importer wants half the order paid up front. The owner uses an unsecured facility to pay the deposit and take the full spring range, repaying it over the season from sales.
How do you stop this happening again?
A supplier failure is a good prompt to reduce single points of failure:
- Keep a second supplier active for critical lines, even at low volume.
- Know which items have no substitute, and hold more of them.
- Watch for warning signs: sudden demands for early payment, missed deliveries, staff turnover.
- Put it in writing — our one-page business continuity plan has a supplier section.
What mistakes make a supplier failure worse?
- Waiting to see if the supplier recovers. Line up alternatives now; you can always switch back.
- Sending a new deposit to a struggling supplier. If they ask for early payment out of the blue, ask why.
- Under-ordering from the new supplier. Running out costs more than carrying a few extra weeks of stock.
- Forgetting goods in transit. Freight already paid for may be sitting at a port or depot — find it.
- Not telling your own customers. A clear message about substitutes or dates keeps orders you’d otherwise lose.
What if the failed supplier also owed you money?
Sometimes the relationship runs both ways — rebates, credits or overpayments owed to you, and invoices you still owe them. Set-off rules can apply in an insolvency, so get advice from your accountant or lawyer before paying or withholding anything.
What documents should you keep?
- Purchase orders, deposits and remittances to the failed supplier
- Correspondence with the administrator or liquidator
- New supplier quotes and terms
- Stock reports
- Bank statements and management accounts
Need working capital to restock?
When a new supplier wants cash up front, a modest working-capital facility can keep the shelves full while terms normalise.
Enquiring is free of credit checks; your file is only looked at once you’ve decided to apply. In a crisis you need fewer calls, not more, so your enquiry stays with one team. Someone who understands crisis recovery reads your enquiry and phones you personally.
Be exact about the figure, the reason, your state and any property in the picture; it saves you a second round of questions. Get the conversation started.
Frequently asked questions
What happens to my deposit if a supplier goes into liquidation?
Usually you become an unsecured creditor for the deposit and lodge a proof of debt with the liquidator. Unsecured creditors are paid after costs and employee entitlements, so recoveries can be small. If specific goods were already set aside for you, ask the administrator whether ownership had passed.
Can an administrator keep supplying me?
Often, yes. Voluntary administrators frequently keep a business trading while they look for a buyer or a deal with creditors. Ask about supply terms, pricing and whether they'll honour existing orders.
How do I find a new supplier quickly?
Ask competitors' suppliers, industry associations and wholesalers, and check whether the failed supplier's own manufacturers will sell direct. Expect tighter payment terms at first.
Can I finance stock when a new supplier wants payment up front?
Yes. Unsecured cash-flow funding or a line of credit sized on your bank statements is commonly used for deposits and stock. Larger amounts can be property-secured.
Should I pay the failed supplier's invoices that are still due?
Get advice before paying or withholding. If the supplier owes you money too, set-off rules may apply. Your accountant or lawyer can tell you where you stand.